Retirement Gap Finder: What It Is and How One Works
Quick Answer
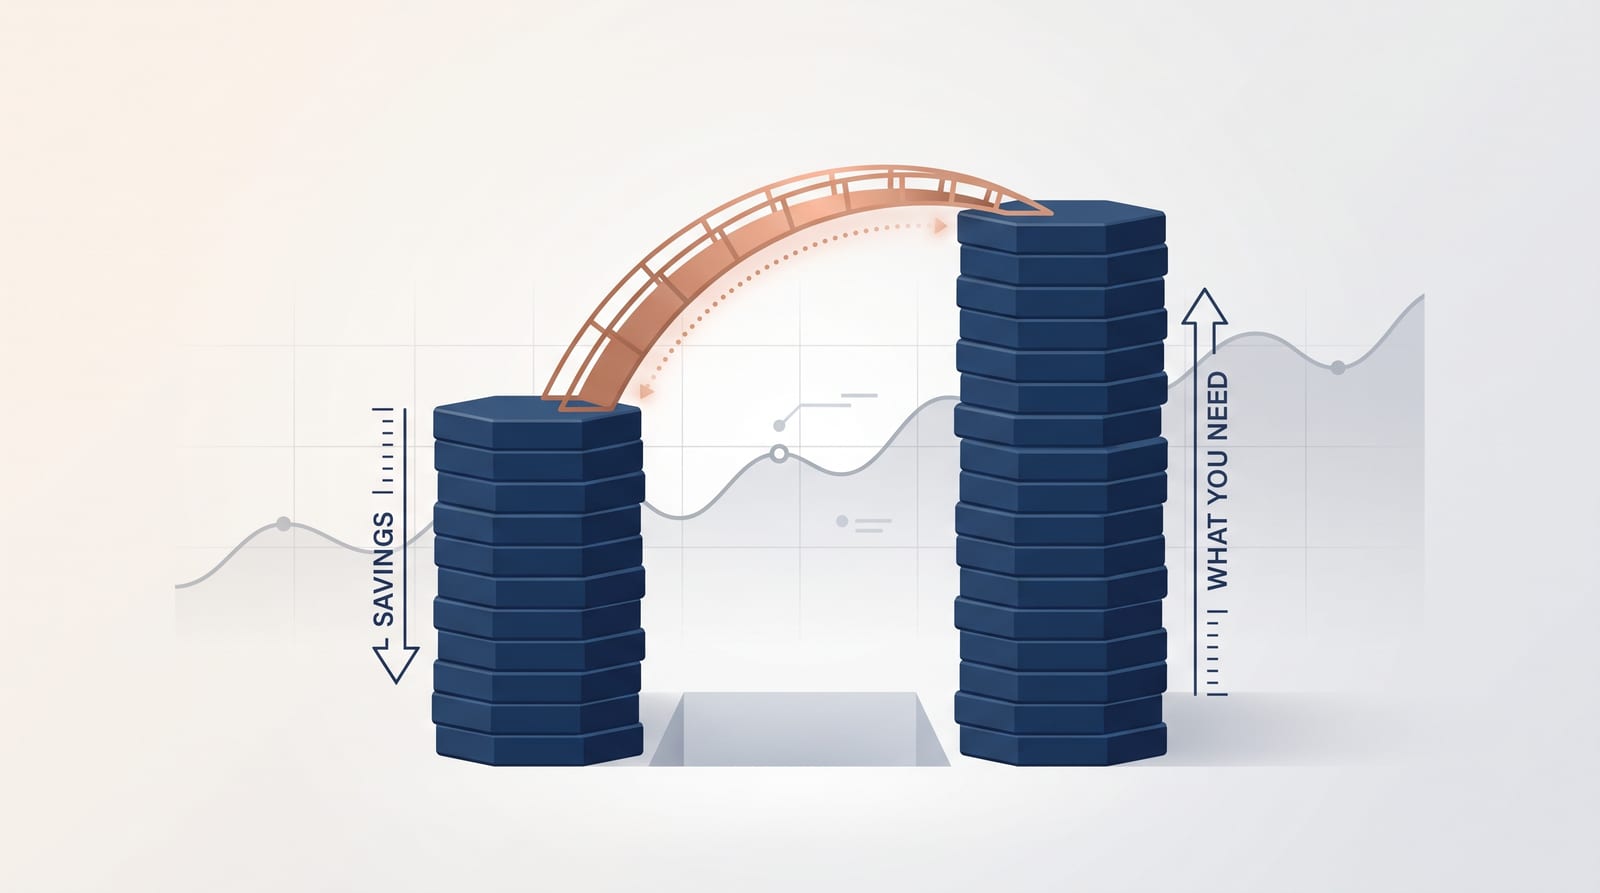
A retirement gap finder is a calculator that estimates the difference between the income you will need in retirement and the guaranteed income you already have coming in, mainly Social Security and any pension. It subtracts one from the other and shows you the shortfall your savings and investments would need to fill. That single number is a good place to start a conversation.
It is not the same as a plan, because it usually assumes you know exactly how long you will live, what your health care will cost, and how much you will spend each year. You do not, and that is fine. The gap is a starting point, not a verdict.
Key Takeaways
- 1 A retirement gap finder subtracts your guaranteed income (mostly Social Security and any pension) from the income you expect to need, and shows the monthly or annual shortfall your savings have to cover.
- 2 It is a useful first number, not a plan. The number changes the moment you change one assumption about how long you live or what you spend.
- 3 Social Security replaces about 40 percent of pre-retirement earnings on average, so for most people a real gap exists whether or not a calculator names it 2.
- 4 Four things decide whether you actually run short, and most gap finders cannot see any of them: how long you live, what health care costs, how taxes and Medicare premiums interact, and how your spending shifts year to year.
- 5 The point of finding the gap is not to be frightened by it. It is to make the number small enough to act on, one decision at a time.
Why This Matters
- For most people, Social Security was never designed to carry the whole load. On average it replaces about 40 percent of pre-retirement earnings, and the share varies with what you earned during your career 2. The average retired worker receives about 2,071 dollars a month after the 2.8 percent cost-of-living increase that took effect in January 2026 1. A dependable check, and rarely a full paycheck. The space between that check and the life you actually want to live is what a gap finder is trying to measure.
- That space is where most retirement anxiety lives, and it is why so many people avoid looking at it. Only 61 percent of workers say they feel confident they will have enough money to live comfortably in retirement, down six points in a single year, and fewer than half say they have even calculated what their health care will cost 7. A gap finder is valuable precisely because it makes you look. Naming the number is almost always less frightening than the fog around it.
- The trouble starts when people treat the number as the finish line. A calculator gives you one figure based on the assumptions it happened to make, and then goes quiet. Real life keeps moving. You might live longer than the tool assumed, face a health event it never priced in, or watch a larger withdrawal quietly push your Medicare premium into a higher bracket. The gap you were shown on a Tuesday afternoon is a snapshot, not a forecast.
- This is the difference between a calculator and a plan. A calculator answers one question once. A plan keeps answering as your life changes, and it holds on to what it learned about you the last time. Grace was built for the second job: to take the gap a calculator hands you and turn it into a retirement wellbeing plan, a set of decisions you can actually make in the order that matters for your situation.
Key Facts
- Social Security replaces about 40 percent of pre-retirement earnings on average, and the exact share depends on your lifetime earnings 2.
- The average retired-worker benefit rose from about 2,015 dollars to about 2,071 dollars a month with the 2.8 percent cost-of-living adjustment effective January 2026 1.
- Among people age 65 and older, 39 percent of men and 44 percent of women receive at least half their income from Social Security, and 12 percent of men and 15 percent of women rely on it for 90 percent or more 3.
- The standard Medicare Part B premium is 202.90 dollars a month in 2026, with an annual Part B deductible of 283 dollars, and this premium is usually deducted straight from the Social Security check 4.
- A man who reaches age 65 today can expect to live about 18 more years on average, and a woman about 21 more years, based on the Social Security period life table 5. Averages mean roughly half of people live longer than that.
- Fidelity estimates that a single 65-year-old retiring in 2025 may spend about 172,500 dollars on health care over the course of retirement, a cost most gap finders leave out entirely 8.
- In 2026 you can contribute up to 24,500 dollars to a 401(k), with a 8,000 dollar catch-up at age 50 and older, and a larger 11,250 dollar catch-up for ages 60 to 63, which is one lever for closing a gap while you are still working 6.
What a gap finder sees, and what it misses
| What the calculator sees | What it usually misses |
|---|---|
| Your Social Security estimate and any pension | How long you will actually live, and the cost of living longer than average [5] |
| A spending target, often a percentage of old income | Health care and long-term care costs that most tools leave out [4][8] |
| A savings balance and an assumed growth rate | How taxes and Medicare premiums rise with larger withdrawals |
| One shortfall number, calculated once | How your spending and your plan change every year afterward |
What a retirement gap finder sees, and the four things it usually cannot [2][4][5][8]
Guaranteed income retirees can count on in 2026
| Figure | 2026 value | Why it matters to your gap |
|---|---|---|
| Average retired-worker benefit | About 2,071 dollars a month [1] | This is often the largest piece of the guaranteed floor |
| Share of income from Social Security, age 65+ | 50 percent or more for 39% of men, 44% of women [3] | Shows how much of the floor most people lean on |
| Standard Medicare Part B premium | 202.90 dollars a month [4] | Comes out of the check, so it shrinks the net floor |
| Annual Part B deductible | 283 dollars [4] | An out-of-pocket cost the guaranteed check does not cover |
The guaranteed income most retirees can count on in 2026 [1][3][4]
Step by Step: What to Do
Step 1: Start with the income you can actually count on
- Pull your real Social Security estimate from your my Social Security account rather than guessing, and add any pension or annuity that pays a fixed amount.
- Remember that the Medicare Part B premium, 202.90 dollars a month in 2026, usually comes out of the Social Security check before it reaches you 4, so use the net figure.
- This total is your guaranteed floor. Everything above it has to come from savings, work, or a decision to spend less.
Step 2: Estimate what you will actually spend, not a rule of thumb
- Popular calculators often assume you will need 70 to 80 percent of your old income. That is an average, and you are not an average.
- Build the number from your real life: housing, food, insurance, travel, helping family, the parts of retirement you are looking forward to.
- Do this before you look at the gap, so the shortfall is measured against your life and not a formula.
Step 3: Find the gap, then read it honestly
- The gap is simple arithmetic: expected annual need minus guaranteed annual income equals the amount your savings must cover each year.
- A gap is normal. Social Security replacing about 40 percent of earnings means most people see one 2, so a number here is not a failing.
- Write it down as a monthly figure. Nine hundred dollars a month is easier to reason about than a frightening lifetime total.
Step 4: Stress-test the gap against the four blind spots
- Longevity: rerun it assuming you live past 90, since a 65-year-old woman lives about 21 more years on average and half live longer 5.
- Health care: add a realistic line for premiums, deductibles, and long-term care rather than the calculator default 48.
- Taxes and Medicare: a larger withdrawal or a Roth conversion can raise your taxable income and your future Part B premium, so the same gap can cost more to fill than it looks.
- Changing spending: your costs are rarely flat, and health expenses tend to climb in later years.
Step 5: Turn the number into a plan you can work
- Decide which levers you control: your claiming age, how much you save now, when you stop working, and how you sequence withdrawals.
- If you are still working, the 2026 catch-up limits let you add up to 8,000 dollars at 50 and older, or 11,250 dollars from ages 60 to 63, on top of the 24,500 dollar base 6.
- For the tax-sensitive moves, bring in a fee-only fiduciary advisor or a retirement-focused CPA who can model your specific brackets before you act.
Real-World Example
 From Grace
When a gap finder hands you a number, the smartest next question is not "how do I save that much." It is "what did this number assume, and which of those assumptions can I change." Here is where to push:
- Ask what age the tool assumed you would live to, then rerun it past 90.
- Check whether health care was included as its own line, and add one if it was not [4][8].
- Test the gap at three different Social Security claiming ages, because that single choice moves the number more than almost anything else.
- Turn the lifetime total into a monthly figure, so the decision feels human-sized instead of overwhelming.
Grace is an AI educational tool, not a licensed financial advisor. This content is for informational purposes only and does not constitute financial, tax, or legal advice. Always consult a qualified professional for decisions specific to your situation.
Frequently Asked Questions
What is the difference between a retirement gap finder and a retirement calculator? +
They overlap. A retirement calculator often estimates whether your savings will last, while a gap finder focuses on the shortfall between the income you will need and the guaranteed income you already have. Both give you one number from one set of assumptions, and neither is a plan on its own.
Is a retirement income gap a sign that I did something wrong? +
No. Because Social Security replaces only about 40 percent of pre-retirement earnings on average [2], most people have a gap by design. It is one reason 39 percent of men and 44 percent of women over 65 rely on Social Security for at least half their income [3]. A gap is a starting point to plan around, not a grade on your past.
Why do free gap calculators give me such different answers? +
Because they make different hidden assumptions about how long you will live, what you will spend, when you will claim Social Security, and whether health care is included. Change any one of those and the gap changes. The number is only as good as the assumptions behind it, which is why it helps to see and adjust them.
How often should I recheck my retirement gap? +
At least once a year, and any time something real changes: a new job, a health event, a market swing, or a decision about when to claim Social Security. A gap you calculated once and never revisited is the least reliable kind, because your life keeps moving and the number should move with it.
Related Articles
Sources
- [1] Social Security Administration, Social Security Administration, 2026 Cost-of-Living Adjustment (COLA) Fact Sheet (2.8% COLA; average retired-worker benefit rising from about 2,015 to about 2,071 dollars a month effective January 2026; taxable maximum 184,500 dollars; earnings test 24,480 dollars under full retirement age) (accessed September 24, 2026)
- [2] Social Security Administration, Social Security Administration, Retirement Ready Fact Sheet for Workers Ages 61-69 ("On average, Social Security will replace about 40% of your annual pre-retirement earnings") (accessed September 24, 2026)
- [3] Social Security Administration, Social Security Administration, Basic Facts fact sheet (among beneficiaries 65+, 39% of men and 44% of women receive at least 50% of income from Social Security; 12% of men and 15% of women rely on it for 90% or more) (accessed September 24, 2026)
- [4] Centers for Medicare & Medicaid Services, Centers for Medicare & Medicaid Services, 2026 Medicare Parts A & B Premiums and Deductibles (standard Part B premium 202.90 dollars a month; annual Part B deductible 283 dollars; Part A inpatient deductible 1,736 dollars) (accessed September 24, 2026)
- [5] Social Security Administration, Social Security Administration, Period Life Table, 2023 (used in the 2026 Trustees Report): life expectancy at age 65 of about 18.1 more years for men and about 20.7 more years for women (accessed September 24, 2026)
- [6] Internal Revenue Service, Internal Revenue Service, IR-2025-111 (2026 401(k) elective deferral limit 24,500 dollars; catch-up 8,000 dollars at 50 and older; enhanced catch-up 11,250 dollars for ages 60-63; IRA limit 7,500 dollars) (accessed September 24, 2026)
- [7] Employee Benefit Research Institute, Employee Benefit Research Institute, 2026 Retirement Confidence Survey (61% of workers feel confident about a comfortable retirement, down 6 points from 2025; fewer than half have calculated retirement health care costs; about 4 in 5 workers are concerned about government changes to the retirement system) (accessed September 24, 2026)
- [8] Fidelity Investments, Fidelity Investments, 2025 Retiree Health Care Cost Estimate (a single 65-year-old retiring in 2025 may spend an average of about 172,500 dollars on health care throughout retirement) (accessed September 24, 2026)
Educational content only. This is not financial, tax, or legal advice. Consult a qualified professional for guidance specific to your situation.